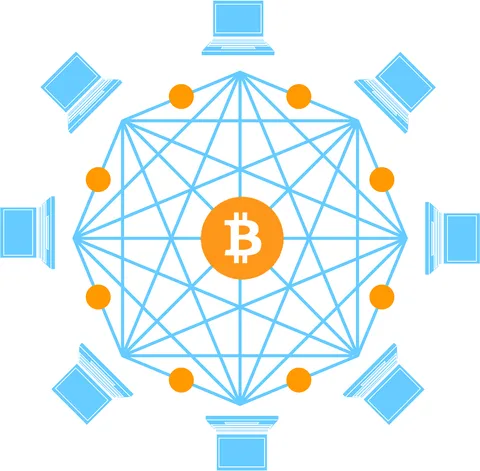
What is Bitcoin? It’s digital money that no bank, company or government runs. Thousands of computers each keep a copy of the same public ledger and check every payment against shared rules, and only 21 million coins can ever exist. In New Zealand it’s legal to own, buy and sell, but it isn’t legal tender.
Picture a notebook that records every payment ever made in a certain kind of money. Instead of a bank keeping it, thousands of people around the world each keep an identical copy, and they all check every new entry against the same rules before writing it down. Nobody can quietly change a page, because everyone else’s copy would disagree.
That shared notebook, and the rules every participant runs on their own computer, are what keep Bitcoin’s records straight without anyone in charge. The sections below explain each moving part, and where a technical term can’t be avoided, it’s defined the first time it appears.
Who created Bitcoin, and when did it start?
Someone using the name Satoshi Nakamoto published the design on 31 October 2008, and the network started on 3 January 2009. Nobody has proven who Satoshi is.
-
The white paper
Someone using the name Satoshi Nakamoto publishes “Bitcoin: A Peer-to-Peer Electronic Cash System”, a nine-page design for money without a trusted middleman.
-
The first block
The network starts. The first block, the genesis block, is mined and the software is released soon after.
-
From hobby to market
Exchanges appear, the price starts to matter, and Satoshi stops communicating publicly. The project carries on without its founder.
-
Fourth halving
The reward for each new block falls to 3.125 BTC, part of a fixed schedule written into the rules.
The white paper appeared in the middle of the global financial crisis, and the timing wasn’t lost on early users. Its pitch was simple: a way for two people to pay each other online without needing a bank in the middle to vouch for them. Satoshi’s identity doesn’t matter for how Bitcoin works. There’s no head office to call.
How does a Bitcoin payment work, from wallet to block?
Your wallet signs a payment, the network checks it, and a miner adds it to the next block. Here’s each stage in turn.
- You sign a message. Your wallet creates a message that says, in effect, “move this amount from my address to that address”, and signs it with your secret key. The signature proves you’re allowed to spend those coins without revealing the key itself.
- The message spreads. Your wallet passes the transaction to computers on the network, called nodes, which check it follows the rules: valid signature, coins not already spent. Valid transactions wait in a queue called the mempool.
- A miner bundles it into a block. Miners collect waiting transactions into a block, prioritising those that pay higher fees. That’s why the fee matters when the network is busy.
- The block joins the chain. Once a miner finds a valid block (more on that below), it’s added to the end of the chain of every previous block. Your payment now has one confirmation, and each new block on top adds another.
A new block arrives roughly every ten minutes on average. That’s slow compared with a card tap, which is one reason the Lightning Network exists (see below).
It’s also why sending Bitcoin feels different from internet banking. There’s no “undo” and no bank to ring if you get the address wrong.
What Bitcoin mining does, and why home mining rarely pays in NZ
Mining decides who adds the next block, and it secures the record against tampering. Miners use specialised computers to make trillions of guesses at a puzzle that can only be solved by trial and error, a bit like trying every combination on a padlock. The first to find a valid answer adds the block and collects a reward: newly created bitcoin plus the fees from the transactions inside. This guessing work is called proof of work, and it’s what makes rewriting history so expensive. To change an old payment, an attacker would have to redo all that work faster than the rest of the network combined.
The puzzle adjusts itself. Every 2,016 blocks, about two weeks, the network resets the difficulty so that blocks keep arriving around every ten minutes, whether more or fewer miners join.
Mining uses a lot of electricity, which is a fair criticism and a frequent debate. For an ordinary New Zealander, mining at home with ordinary hardware isn’t economic.
Why only 21 million bitcoin can ever exist
Bitcoin’s rules fix the total at 21 million, and new coins enter circulation only as mining rewards. That reward halves every 210,000 blocks, roughly every four years. It started at 50 BTC per block, and since the halving in April 2024 it has been 3.125 BTC. The rewards keep shrinking until, well over a century from now, no new bitcoin will be created and miners will rely on fees alone.
Changing the cap would need almost everyone running Bitcoin software to agree to new rules, which is why people treat it as fixed. A fixed supply doesn’t make the price go up, though. Price depends on how much people want to hold it, which can change quickly in either direction. The halving and market numbers are tracked on our live Bitcoin price in NZD page.
Each coin also splits into 100 million sats, so the cap doesn’t stop anyone buying a small amount. At a hypothetical price of NZ$100,000 per bitcoin, NZ$1 buys 1,000 sats; the live BTC/NZD page shows today’s figure.
What does a Bitcoin wallet actually hold?
A private key, not coins. The coins live on the shared ledger, and the wallet holds the very large secret number that lets you sign spending messages for your addresses. Most people get this wrong, and it shapes everything about keeping Bitcoin safe.
Private key
The secret that lets you spend. Whoever has it controls the coins. Never share it with anyone.
Recovery phrase
12 or 24 ordinary words that back up your keys. Write it on paper; never photograph it or type it into a website.
Address
Like an account number you can share so people can pay you. Safe to give out; it can’t be used to spend.
That leads to the most important practical choice in Bitcoin. If an exchange holds the keys for you, it’s a custodial arrangement: convenient, but you’re trusting the company. If you hold them yourself, it’s non-custodial: nobody can freeze your coins, but nobody can recover them if you lose the phrase either.
The trade-off, with New Zealand examples, is laid out in our custodial vs non-custodial guide, and the Bitcoin wallets available to Kiwis are compared separately.
How the Lightning Network makes small Bitcoin payments fast
Ten-minute blocks and variable fees are fine for moving savings, less so for buying a coffee. The Lightning Network is a second layer built on top of Bitcoin. Two parties lock some bitcoin into a shared channel recorded on the main chain, then pay each other back and forth instantly off-chain, settling the final balance on the main chain later. Payments can hop across a network of connected channels, so you don’t need a direct channel with every shop.
In practice you just use a Lightning-enabled wallet and scan a QR code; payments usually arrive in seconds with tiny fees. A small number of New Zealand businesses accept Bitcoin, many of them via Lightning, with a notable cluster in Queenstown. Lightning is newer and less battle-tested than the main chain, so it suits spending money rather than large balances.
Is Bitcoin anonymous, a company or legal tender? Six common myths
- Not a company. There’s no Bitcoin Ltd, no chief executive and no customer service line. Anyone claiming to be “from Bitcoin” is not.
- Not legal tender in New Zealand. Shops don’t have to accept it, and few do.
- Not anonymous. Every transaction is public. Addresses aren’t names, but once one is linked to you, for example through an exchange that verified your ID, your history can often be traced.
- Not a bank deposit. No interest, and no deposit insurance or government guarantee.
- Not the same as “crypto”. Bitcoin was the first cryptocurrency. Thousands of other coins and tokens followed, with different rules, teams and risks.
- Not a way to get rich quick. Anyone guaranteeing Bitcoin returns is almost certainly running a scam.
Bitcoin’s strengths, and the risks New Zealanders have already seen
What works
- Runs around the clock with no central operator to shut it down
- Fixed, publicly known supply rules
- You can hold it yourself without a bank
- Can be sent anywhere in the world
Watch out for
- Price swings are large and frequent; it can fall a long way and stay down
- Mistakes are permanent: wrong address, lost recovery phrase
- Exchanges can fail or be hacked, as Cryptopia and Dasset showed in NZ
- A favourite tool of scammers, because payments can’t be reversed
- Rules and tax treatment keep changing
Is Bitcoin legal in New Zealand, and is it taxed?
Yes, it’s legal. Owning, buying and selling Bitcoin is lawful in New Zealand, but it isn’t a free-for-all. Businesses that exchange or hold crypto for customers generally have to register on the Financial Service Providers Register and follow anti-money-laundering rules, which is why they check your ID.
Since 1 July 2026 the Department of Internal Affairs has been the single anti-money-laundering supervisor. New Zealand’s High Court has also treated crypto as property, in the Cryptopia liquidation. Keep the FMA’s consumer warning in mind: money lost to crypto scams is often not recovered. Our guide to whether crypto is legal in NZ has the full picture.
It can be taxable. IRD treats crypto as property. If you buy Bitcoin intending to sell or swap it, which IRD says is usually the case for an asset that produces no income, the profit when you dispose of it is generally taxable at your normal income-tax rate. Buying and selling crypto itself isn’t subject to GST. Keep records from day one; the IRD rules on crypto, with worked examples, are in our tax guide.
Bitcoin’s key numbers at a glance
| Fact | Figure |
|---|---|
| White paper published | 31 October 2008 |
| Network started | 3 January 2009 |
| Maximum supply | 21 million BTC |
| Smallest unit | 1 sat = 0.00000001 BTC |
| Average time between blocks | About 10 minutes |
| Difficulty adjustment | Every 2,016 blocks, about two weeks |
| Halving interval | Every 210,000 blocks, about four years |
| Block reward since April 2024 | 3.125 BTC |
| Recovery phrase length | 12 or 24 words |
| Status in NZ | Legal to own; not legal tender; IRD treats it as property |
If those ideas make sense, you understand more than most people who own Bitcoin. Deciding to buy some? Start small, practise withdrawing to your own wallet, and keep good records; our beginner’s guide to buying Bitcoin in NZ picks up from here. And if you decide it isn’t for you, that’s a perfectly reasonable conclusion too.
Questions Kiwis ask
What is Bitcoin in simple words?
Bitcoin is a type of digital money that works without a bank. Instead of one company keeping the records, thousands of computers around the world each keep a copy of the same ledger of payments and check every new payment against the rules. Only 21 million coins can ever exist, and you control yours with a secret key held in a wallet.
Who created Bitcoin?
Someone using the name Satoshi Nakamoto published the Bitcoin white paper on 31 October 2008 and released the software in January 2009. Nobody has proven who Satoshi is, and the creator stopped communicating publicly in the early years. Bitcoin doesn’t depend on its founder; it’s maintained by volunteers and run by its users.
Is Bitcoin real money?
It’s used as money by some people, and you can spend it at a small number of New Zealand businesses, but it isn’t legal tender here. Nobody has to accept it, and IRD treats it as property for tax rather than currency. Its value comes only from what people are willing to pay for it.
How does Bitcoin make money for people?
Bitcoin itself pays no interest or dividends. People who make money from it usually do so by selling for more than they paid, which in New Zealand is often taxable. Others lose money when the price falls. Anything promising guaranteed Bitcoin returns is a red flag for a scam.
Is Bitcoin anonymous?
No, it’s pseudonymous. Every transaction is visible on a public ledger linked to addresses rather than names. Once an address is connected to you, for example through an exchange that verified your ID, your history can often be traced. IRD has said people are not invisible on the blockchain.
Can Bitcoin be hacked?
The Bitcoin network itself has proved very hard to attack. What gets hacked are the things around it: exchanges, people’s devices, phishing sites and scams that trick you into revealing your recovery phrase. New Zealand’s Cryptopia exchange was hacked in 2019, but that was the company’s wallets, not Bitcoin.
Sources and dates
We link to primary sources wherever they exist. Where only a secondary source was available, we say so in the text.
- Satoshi Nakamoto — Bitcoin: A Peer-to-Peer Electronic Cash System 31 Oct 2008
- Bitcoin developer guide — blockchain, proof of work and block subsidy checked 16 Oct 2026
- mempool.space — live blocks and network data live
- Lightning Network checked 16 Oct 2026
- IRD — Cryptoassets checked 16 Oct 2026
- IRD — Crypto investors urged to get tax compliant 20 Apr 2026
- IRD — Cryptoassets and GST updated 30 Aug 2022
- FMA — Cryptocurrencies (consumer guidance) checked 16 Oct 2026
- Ministry of Justice — AML/CFT legislative changes updated 14 Jul 2026
- Hesketh Henry — High Court recognises property in cryptocurrency (Ruscoe v Cryptopia) 2020